The latest news, trends, analysis, interviews and podcasts from the global food and beverage industry



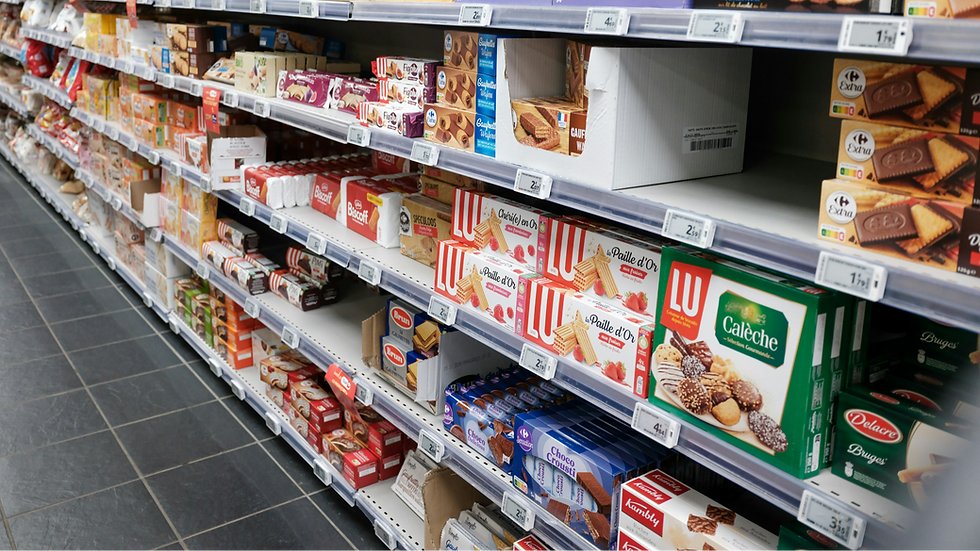
The French government has proposed a plan to extend its sugar tax on soft drinks to include high-sugar processed foods, a measure aiming to improve public health across the nation.
In its 2027 budget, France’s government noted that industrially processed foods containing additives – often referred to as ultra-processed foods (UPFs) – are major contributors to excessive sugar consumption.
It proposes the extension of its sugar levy, which currently covers sweetened non-alcoholic drinks, as part of measures to tackle the root cause of chronic diseases linked to high-sugar diets, such as diabetes and cardiovascular conditions.
The proposed extension would operate on a sliding scale based on sugar content. The government said it aims to safeguard ‘high-quality food produced by our farmers, as well as artisanal products’.
The budget states that 40% of adults and 80% of children in France consume too much sugar, while consumption of processed foods has risen by 170% since the 1980s.
Impact on industry
Commenting on the proposed measure, Paul Boivin, director general of national bakery, viennoiserie and pastry sector association Fédération des Entrepreneurs de Boulangerie (FEB), told FoodBev: “Reducing excessive sugar consumption is a major public health priority. Manufacturers of bakery and patisserie products have a responsibility to contribute, and we accept that responsibility.
“However, FEB opposes the proposed extension of the tax. We believe the government should recognise and support the collective sugar reduction work already undertaken by our federation with its own administrations. For more than a year, our sector has worked with the Ministry of Health and the Ministry of Agriculture on a voluntary agreement for industrial pastries and viennoiseries.”
A voluntary agreement submitted by the FEB’s members is being submitted, aiming to reduce the average sugar content of their product offer by at least 5% by 2031, Boivin pointed out. This aims for ‘actual sugar reduction’ without compensating by using substitutes or additives.
But Boivin argues that taxing products without recognising companies’ existing reformulation efforts “sends a contradictory message”, adding: “A tax alone does not guarantee a lasting improvement in diets. It is dishonest to suggest otherwise in an attempt to justify a tax in disguise.”
He expressed concerns about small and medium-size enterprises’ capacity to invest, facing additional costs on top of recipe development, production trials and product testing.
“The tax would also create an uneven playing field between pre-packaged products and products sold loose,” Boivin said. “Comparable products with the same sugar content could be treated differently simply because of how they are packaged and sold. We see no public health justification for such a difference in treatment.”
Product quality can become significantly impacted when reformulating to reduce sugar, due to its functional role in areas beyond sweetening. Sugar can also contribute to texture, appearance and shelf life, and Boivin noted that preserving quality is critical in successfully reformulating while helping consumers become accustomed to less sweet flavours.
“The risk is that the tax absorbs resources needed to achieve these changes. Businesses could have to absorb the cost through lower margins or pass some of it on to consumers,” he concluded.
Sugar reduction ramps up around Europe
Legislation around sugar reduction has broadened substantially in Europe over the last decade, though most levies currently in place focus on sweetened beverages.

The UK government announced plans to extend its Soft Drinks Industry Levy last year, covering additional beverage categories including dairy drinks and RTD coffees in addition to traditional fizzy drinks and fruit squash products.
Additionally, the threshold for sugar levels was lowered from 5g to 4.5 per 100ml, with manufacturers given until 1 January 2028 to reduce sugar in their drinks to avoid the tax.
The Soft Drinks Industry Levy has seen the average sugar content of drinks in scope drop by almost 50% since its introduction in 2018.
However, the UK has not yet gone as far as to extend the levy to cover food products. Instead, measures to reduce sugar consumption in foods have focused on marketing and product placement restrictions.
A UK report, published last March, called for a new sugar and salt tax on industrially processed foods such as biscuits, breakfast cereals and crisps, with Chris Hilson, lead author of the report at the University of Reading, calling an extension of the legislation “vital” in improving public health.
Elsewhere, Poland has recently proposed an expansion of its sugar tax to cover more beverage formats, including concentrates and ready-to-drink dietary supplements. If approved, the changes would take effect from 1 January 2027.
Germany has also proposed the introduction of a new soft drinks sugar tax from 2027, though manufacturers have criticised the proposal, stating that an accelerated timetable – with the legislation previously proposed for implementation in 2028 – could have significant financial consequences for businesses and leave them too little time to prepare.